All Categories
Featured


Budgeting and Credit Counseling Strategies
Table of Contents
Closing credit cards to "start fresh"Ignoring balances and hoping ratings repair themselvesApplying for multiple new accounts to balance out debtThese relocations usually slow recovery instead of helping it. If you're not exactly sure where to start, you do not have to figure it out alone. Langley offers tools and resources to support healthier credit practices, consisting of: to assist keep payments on timeSavings-building tools like the Educational covering credit, financial obligation, and financial fundamentals Vacation spending does not define your monetary future.
Guide to Credit Repair Laws 2026Holiday costs often impacts credit history through greater balances or missed out on payments Many credit rating drops are temporary Paying for balances and staying constant assists ratings rebound Tools like Langley's Credit Contractor Loan can support long-lasting recovery.
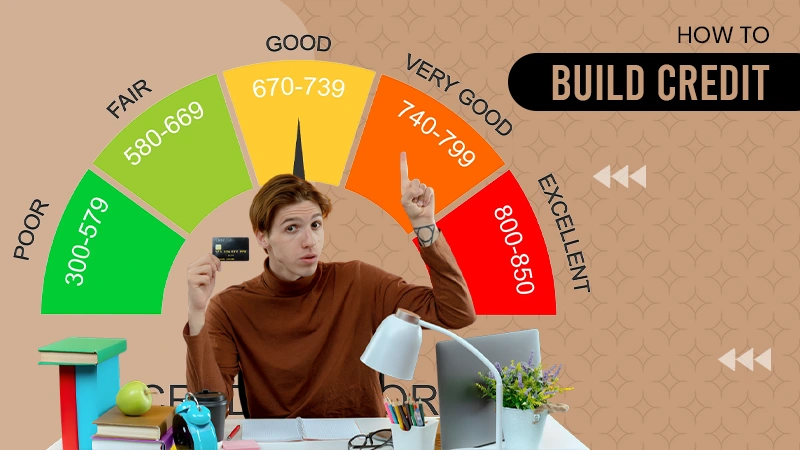
Good credit can make it easier to do anything from lease an apartment or condo to receive a lower rate on a cars and truck loan. On the other hand, bad credit can be a challenge to accomplishing your goals. When your credit history is a barrier to the monetary life you desire, business promising credit repair work may appear like saviors.
Strategic Score Building Tips for ConsumersYour Consumer Rights Under Modern Credit Laws
Credit repair work companies frequently charge large charges to find and dispute negative information on your credit reports. The bright side is you don't have to pay anybody to repair your credit. You can fix your credit totally free by examining your credit report and taking measures to enhance your credit rating.
Errors in credit reports are uncommon but might appear from time to time, and depending upon the info included, could negatively impact your credit history. Evaluating your credit report from each of the three major credit bureaus (Experian, TransUnion and Equifax) a minimum of once a year helps you spot issues.
Evaluation your credit report for the following: Open credit accounts and accounts closed for up to 10 years appear on your credit report. Incorrect negative details, even if it's simply a late payment that was really paid on time, might lower your credit score. Errors in individual info, such a name or address reported incorrectly by a creditor, will not impact your credit rating however must still be fixed.
You can dispute errors in your Experian credit report online, by mail or by phone; TransUnion and Equifax have their own disagreement processes. When you file a disagreement, Experian asks the company that supplied the contested information to inspect their records. Inaccurate info will be fixed; details that can't be validated will be erased or updated.
Essential Financial Literacy in 2026
Due to the fact that payment history is the biggest factor in your credit score, even one late payment can reduce your score. Late payments remain on your credit report for approximately 7 years. If you're late but not yet 30 days behind on a payment, pay it right away. If the payment is currently 30 or more days past due, bring the account current as quickly as possible.
Can't manage to make the payment? Payment history accounts for 35% of your FICO Score, so once your accounts are all present, keep them that method by setting up autopay.
Preferably, however, you must pay the balance in full every month. Make certain there's adequate cash in your account to cover all your autopays to avoid overdrafts or inadequate funds transactions. Your credit utilization rate procedures how much revolving credit you're utilizing relative to your overall credit limits. Credit utilization accounts for approximately 30% of your credit report.
Ways to Fix My Credit Fast in 2026
Do this for each card you hold and for the overall of all your charge card. If your usage rate is 30% or more total or on a single account, pay down your charge card balances to see a prospective boost to your credit rating. The lower your credit usage, the better.
Your details stays personal. We'll detect bills with on-time payments, and you can include them to your Experian credit file. You'll learn right now if your credit ratings increased and by how numerous points. Outcomes will vary. Not all payments are boost-eligible. Some users might not get an improved rating or approval odds.

Discover more. If you're bring debt balances, make a plan for paying them down. Not just is high-interest debt costly, however the quantity of debt you carry has an effect on your rating. Here are some concepts for how to settle financial obligation: Another choice is to consolidate your debt.

Latest Posts

Access Free Financial Counseling Near Me
Essential Financial Literacy Concepts for Adults in 2026
Your Consumer Rights Under Modern Credit Laws